

Flood Insurance in Colorado and Arizona
No home, condo or renters policy covers flood. Anywhere, from any carrier. In burn scar and monsoon country that gap is a great deal more real than the flood maps suggest.
The Exclusion Every Other Policy Shares
It is worth stating plainly, because it catches people every year: flood is excluded from every standard home, condo and renters policy. Not limited, not capped. Excluded. If water arrives across the ground rather than through your roof, none of those policies respond.
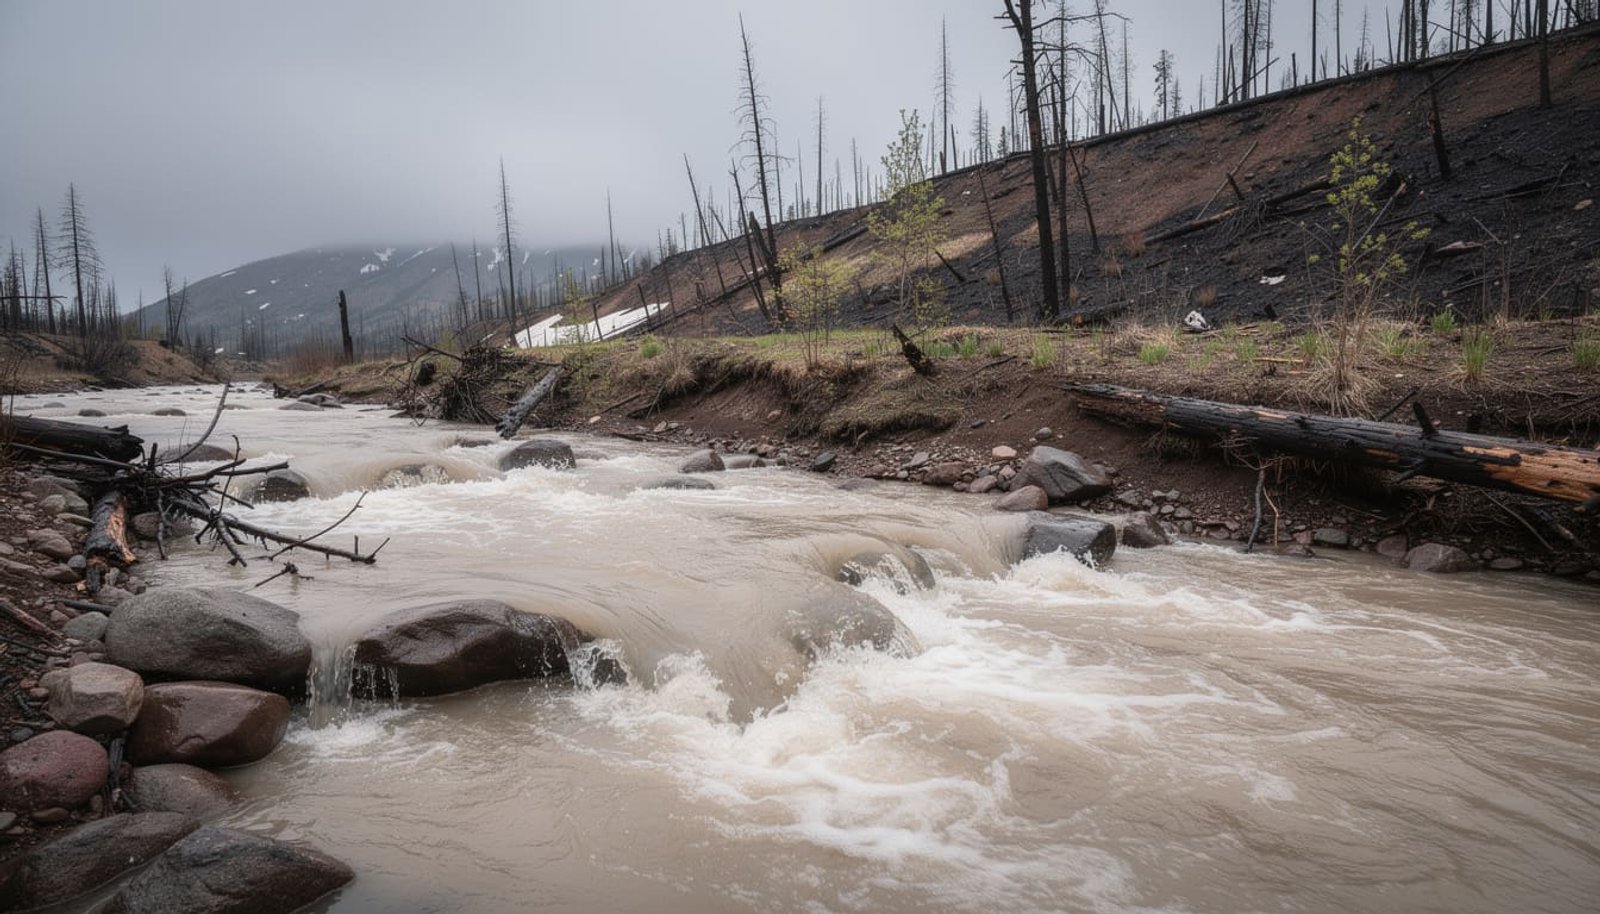
In Colorado the risk is not really about rivers. It is about burn scars. Ground stripped by wildfire sheds water instead of absorbing it, and a normal afternoon storm above a burn area can send debris flow through properties that have never flooded and sit nowhere near a mapped flood zone. Arizona has its own version in monsoon season, where washes fill in minutes. A large share of flood claims come from outside high-risk zones.
Coverage comes either through the federal NFIP programme or from private carriers, and the two differ on limits, contents and waiting periods. We can place both, across Colorado and Arizona.
- Coverage nationwide
- NFIP and private options
- Burn scar risk assessed
What Flood Coverage Can Include
Flood policies are structured differently from the rest of your insurance. These are the parts that matter most.
Building Coverage
The structure itself, plus the systems in it: furnace, water heater, electrical and permanently installed fixtures and cabinetry.
Contents Coverage
Your belongings, and it is separate from building coverage. Buying one without the other is a common and expensive oversight.
Debris Removal
Flooding leaves mud and wreckage behind. Clearing it is a genuine cost, particularly with debris flow off a burn scar.
Basement Limitations
Below-grade coverage is restricted, especially for contents and finishes. Understand the limits before you finish a basement, not after.
Private Flood Options
Private carriers can offer higher limits than the NFIP caps and sometimes shorter waiting periods. Worth comparing against the federal option.
Preferred Risk Pricing
Properties outside high-risk zones often qualify for markedly lower rates. Being off the map is a pricing advantage, not a reason to skip coverage.
Flood policies typically carry a 30 day waiting period before coverage begins, so this is not something to arrange when rain is forecast. Standard home, condo and renters policies exclude flood entirely. Coverage terms and payouts depend on your policy and the carrier.
Getting a Flood Quote Is Simple
Start well before you think you need it, because of the waiting period.
Start Your Free QuoteWe Listen
The address, roughly when it was built, whether there is a basement, and what is upslope of you.
01
We Shop
We check your flood zone and burn scar exposure, then compare NFIP against private carriers on limits and price.
02
You Choose
You see both routes side by side and choose. Remember coverage usually starts 30 days later.
03
Flood Insurance Questions We Hear a Lot
No. Flood is excluded from every standard home, condo and renters policy, from every carrier. A burst pipe inside the house is a different thing and may well be covered. Water arriving across the ground is not. See home insurance.
Possibly, and Colorado is the reason. Burn scars change how land sheds water for years after a fire, and properties well outside mapped zones have flooded from debris flow. A large share of claims nationally come from lower-risk areas.
Usually 30 days for NFIP policies, with limited exceptions such as a loan closing. Some private policies are quicker. Either way you cannot buy it with a storm on the forecast, which is exactly when people try.
Below-grade areas have real coverage restrictions, particularly for finished walls, flooring and contents. Essential building systems are treated more favourably. It is worth understanding before you finish the space.
NFIP is the federal programme with set caps. Private carriers can exceed those limits and occasionally offer shorter waiting periods, though availability varies by property. We can quote both and compare them for you.
Contents-only flood coverage exists and is inexpensive. If you rent somewhere below a burn scar or near a wash, it is worth considering, because your renters policy will not respond to flood.
What Our Clients Say
- Personal coverage · Great service
Really GREAT group to work with - Kim Adams is a "GSD" Queen!! This group really makes you feel like you have people on your side in all the madness of the insurance world....... thank you for all your many years of help and we APPRECIATE your integrity and outstanding service. A+++++++++
Christine Bergman Google - Personal coverage · Great service
I have had great service from Pikes Peak Insurance-from the owners to other staff. Recently Melinda went out of her way to help me. As have others. She has kept in touch and as I am now older it is greatly appreciated. They are at a milestone anniversary and I wish them great success into the future.
Sandra Davis Google - Business insurance · Great service
Krys has been our insurance agent for years now, and has helped us every step of the way! The communication is fantastic and customer service is top notch! Thank you PPIA
TCS Septic Google - Personal coverage · Great service
Gretchen, Kim, and the entire staff at Pikes Peak Insurance have consistently provided me with top-notch customer service over the past 20 years. They have the perfect blend of professional expertise and thoughtful regard for the well-being of their clients.
Debbie Evercloud Google - Personal coverage · Great service
I can't say enough great things about Pikes Peak Insurance Agency! Every time I call with questions about something, they are all so kind and helpful. Especially Gretchen! She remembers who I am right away and is just the sweetest! She's knowledgeable and extremely helpful, always looking for the best solution for their clients. I highly recommend this company!
Tina Google - Personal coverage · Great service
I have been working with the Pikes Peak Insurance agency for more than a decade. Chris, Barbara, Gretchen, Donald are all very professional and find best insurance policies that work for me. I am very happy with their service. They do a good job.
Sarma Yeddanapudy Google
Ready for a Free, No-Pressure Quote?
Call or text (719) 591-4500, or request your quote online. One local team, more options, and no obligation. Open M–F · 9:00 AM–5:00 PM.
Request Your QuoteShort on Time? Have Us Call You.
No quote form to fill out. Leave your name and number and someone from our Falcon office will call you back.